

A day or two after a truck crash, your phone rings. The caller is friendly, sounds official, and says they just need a “quick statement” to move your claim along. Before you say a word: no, you should not give a statement after a truck accident to the trucking company or its insurance adjuster — not yet, and not without knowing who you’re really talking to.
That call feels routine. It isn’t. In a Las Vegas truck accident, the person on the line usually works for the trucking company or its insurer, and their job is to protect the carrier’s money — not yours. Saying “no thank you” is not rude, and it does not make you look guilty. It’s one of the smartest things you can do to protect your claim.
Who’s Actually Calling You — and Why So Fast
After a normal fender-bender, a claims adjuster might reach out in a few days. After a commercial truck crash, the calls come faster and hit harder, because you’re not dealing with one driver — you’re dealing with a company.
Big carriers keep a rapid-response team on standby: investigators, and sometimes defense lawyers, who start building the company’s case within hours of a crash. Part of that playbook is getting you talking early, while you’re shaken, in pain, or medicated, and before anyone knows how badly you’re hurt.
So when “the insurance” calls, ask yourself whose insurance it is. If it’s the trucking company’s insurer, the truck’s own insurer, or an adjuster you’ve never dealt with, that’s the other side. They are not calling to help you heal. They’re calling to lock in your words before you understand your own case.
No — You Don’t Have to Give a Statement After a Truck Accident to the Trucking Company
Here’s the part the adjuster won’t volunteer: you are under no obligation to give a recorded statement to the at-fault trucking company’s insurance company. It doesn’t matter how “standard” they make it sound. You can decline, and your claim continues.
Nevada is an at-fault state, which means the driver or company that caused the crash — and their insurer — is responsible for the harm. You are the one bringing the claim against them. You owe the other side’s insurer a cooperative interview about as much as you’d owe the opposing team your game plan. A polite “I’m not giving a statement right now” is a complete answer.
What you say to that adjuster can be used to chip away at what you’re owed. That’s not a suspicion — it’s the entire reason for the request.
Why a Statement Is Even Riskier in a Truck Case
Giving an early statement is risky after any crash. In a truck case, three things make it worse.
They’re hunting for fault to shift onto you. Nevada uses a comparative-fault rule, so the trucking company has a direct financial reason to pin part of the blame on you. Every percentage of fault they push onto you can cut what they pay. Adjusters are trained to ask friendly-sounding questions designed to get you to say something that sounds like an admission.
You don’t know how hurt you are yet. Truck-crash forces are violent, and serious problems — spinal damage, a brain injury, internal injuries — don’t always show up at the scene. If you tell an adjuster you feel “okay” on day two, they will replay that later, after the injuries that show up days later finally surface, to argue you were never really hurt.
There isn’t just one insurer. A commercial crash can involve the driver, the motor carrier, the trailer owner, a maintenance company, and the cargo loader — each with its own policy. A single loose sentence can be passed around and used by several insurers at once. Sorting out who’s on the hook is exactly the kind of thing your Las Vegas truck accident lawyer handles, and it’s far harder to do after you’ve already talked.
The One Exception: Your Own Insurer
There’s a real difference between the trucking company’s insurer and your own.
Your own auto policy almost certainly has a “cooperation clause” — a term you agreed to that can require you to give your insurer a statement, especially if you’re using your uninsured/underinsured motorist coverage or medical-payments benefits. Stonewalling your own insurance company is different from declining the other side’s, and refusing to cooperate with your carrier can put your own benefits at risk.
That doesn’t mean you go it alone, though. Even with your own insurer, you have the right to have a lawyer help you prepare, or handle the conversation for you, so a routine statement doesn’t accidentally hurt a claim you’re also making against the trucking company. When in doubt about which insurer is which, that’s a two-minute question for an attorney before you say anything.
What to Say When They Call: The Simple Script
You don’t need to be confrontational. You need to be brief. Here’s how to handle the call without hurting your case:
- Stay polite, stay short. “I’m not ready to give a statement. Please send any requests in writing.” You never have to explain yourself.
- Get their information. Write down the caller’s name, the company they represent, and any claim number. That’s useful to you later.
- Don’t sign anything. Especially a blanket medical authorization — it can hand the trucking company your entire medical history to dig through for anything they can twist against you.
- Don’t accept a fast offer. An early check is almost always below what your claim is worth, and cashing it can end your case for good.
- See a doctor if you haven’t. Getting examined protects your health and ties your injuries to the crash before anyone can dispute them.
- Then hand it off. Let a lawyer deal with the carrier so you never have to take that call again.
If you want the bigger picture on your first moves, our guide on what to do after a Nevada truck accident walks through the full checklist.
Why Handling the Call Quickly Protects Your Case
While the adjuster keeps you talking, a clock is running on the evidence that proves what really happened. The truck’s black box and electronic logs — the data showing speed, braking, and how long the driver had been behind the wheel — sit inside the truck and inside the carrier’s files. Much of it can be legally overwritten or discarded within weeks, and the trucking company is in no hurry to preserve what might sink its defense.
A lawyer’s first move is to send a formal preservation letter that legally requires the carrier to hold that evidence. That’s why “I’ll deal with the insurance later” can quietly cost you the case. You generally have two years to file a Nevada truck accident claim, but the proof can vanish long before that deadline — more on that timeline in our post on how long a truck accident claim takes. The sooner someone acts for you, the more survives.
How Howard Injury Law Takes the Call Off Your Hands
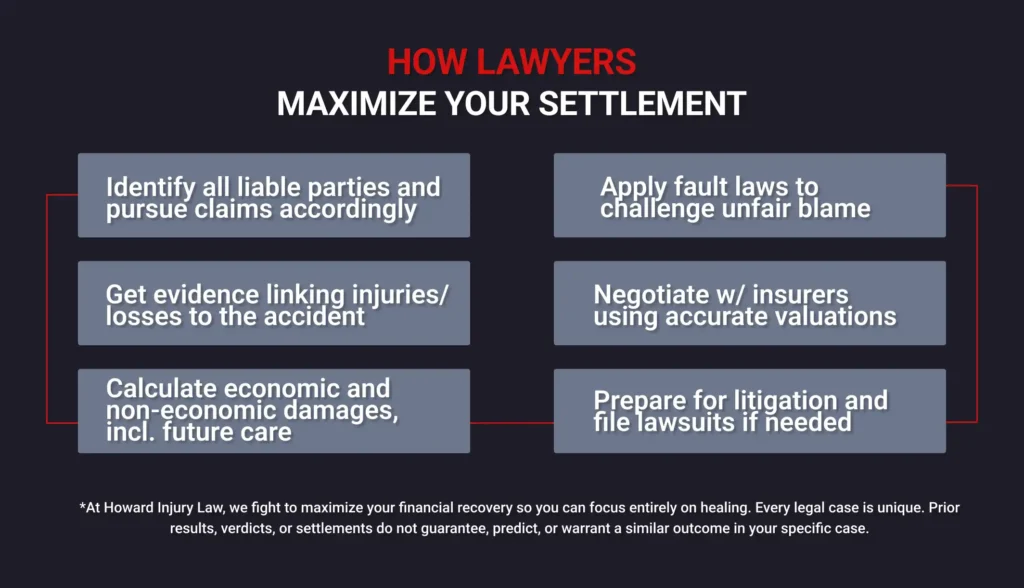
The single most reassuring thing to know is this: once you have a lawyer, the trucking company’s insurer calls us, not you. You go back to healing. We handle the statements, the paperwork, and the finger-pointing between insurers.
There’s a reason that matters here. Glen Howard built his career on the other side of these claims — as an insurance-defense attorney. He knows the script the carrier’s adjuster is reading from, the questions engineered to trip you up, and how the other side decides what a claim is worth, because he used to sit in that chair. Now he uses that playbook for injured Las Vegas drivers and families instead of against them.
That experience is part of why the firm has recovered more than $80 million for Nevada injury victims, always on contingency — no fee unless we win. You don’t pay to find out where you stand.
Every truck case is different, and this is general information, not legal advice about your specific situation. The fastest way to know how it applies to you is to ask.
Frequently Asked Questions
Do I have to give the trucking company’s insurance a recorded statement?
No. You are not required to give a recorded statement to the at-fault trucking company or its insurer, no matter how routine they make it sound. They’re not asking to help you — they’re gathering material to reduce or deny what they owe. You can politely decline, ask them to put any request in writing, and refer them to your attorney. Your claim keeps moving without that statement. The only situation where a statement may be required is with your own insurance company, and even then you can have a lawyer prepare you or handle it for you.
What happens if I don’t give my own insurance a statement?
Your own policy is different from the trucking company’s. Most auto policies include a cooperation clause that can require you to give your insurer a statement, especially when you’re claiming uninsured/underinsured motorist or medical-payments benefits. Refusing to cooperate with your own carrier can jeopardize those benefits. That still doesn’t mean you should wing it alone — you have every right to have a Las Vegas truck accident attorney prepare you or speak with your insurer for you, so a routine statement doesn’t accidentally weaken a claim you’re also bringing against the trucking company.
What should I not say to a truck accident insurance adjuster?
Don’t guess, don’t speculate, and don’t minimize. Avoid saying “I’m fine” or “I’m okay” — truck-crash injuries often surface days later, and that quote will be used to argue you weren’t hurt. Don’t admit any fault or theorize about what happened, don’t give a detailed injury rundown before a doctor has examined you, and don’t agree to a recorded statement or sign a medical authorization. The safest approach is to keep the call short, share only basic facts like your name and that a crash occurred, and let your lawyer handle the rest.
Should I talk to the other driver’s insurance company at all?
You can confirm basic facts — that a crash happened and your contact information — but you’re not obligated to give the at-fault side a recorded statement or a detailed account, and it’s usually a mistake to try. Adjusters do this all day and know how to steer a “friendly chat” toward answers that help the trucking company. Anything you say can be used to shift blame or shrink your claim. The cleanest move is to decline the statement, take down who’s calling, and let your attorney handle every conversation with the other side’s insurer from that point on.
Talk to a Lawyer Before You Talk to Them
If the trucking company or an adjuster has already called — or you’re bracing for the call — get ahead of it before you say something you can’t take back. A free, no-obligation consultation gives you a straight answer on whether you have a case, what your claim may be worth, and who you should (and shouldn’t) be talking to. You can also have us deal with the trucking company from here, so the next time they call, they reach your attorney — not you.