

A serious pileup on I-15 can leave four or five people hurt — and one at-fault driver carrying nothing but Nevada’s minimum insurance. If that describes your crash, the fear is real and specific: there may not be enough money to cover everyone, and you’re worried you’ll be left holding bills for an injury that wasn’t your fault. Here’s the part most people don’t hear first: when one policy can’t cover everyone injured, that policy is rarely the only place your compensation can come from. A Las Vegas multi-vehicle accident lawyer’s job is to find every source of coverage before anyone tells you to settle for less.
Nevada is an at-fault state, so the driver who caused the crash — and their insurance — is responsible for the harm. The problem isn’t who owes you. It’s whether one small policy can stretch far enough.
Why one insurance policy often isn’t enough after a multi-vehicle crash
Nevada law only requires drivers to carry 25/50/20 liability coverage under NRS 485.185: $25,000 for one person’s injuries, $50,000 total per crash, and $20,000 for property damage. Those limits have been in place since 2018 and haven’t changed. They were built for fender-benders, not for the crashes that send several people to Sunrise or UMC.
The number that hurts victims most is the middle one. That $50,000 is a single pot for everyone injured in the crash — not $50,000 per person. When a chain-reaction wreck injures four people, that same $50,000 has to cover all four. A single trauma admission, one surgery, or an air-ambulance ride can burn through it before the other victims see a dollar.
Chain-reaction crashes make the math worse because they multiply the injured. One act of negligence — a distracted driver, an unexpected hazard, inadequate stopping distance in stop-and-go traffic, low visibility from dust or glare on the 215 Beltway — sets off a wreck that involves three, four, or more vehicles. More cars mean more people, and the same thin policy split more ways. If you want the full picture of how these crashes unfold and who answers for them, our chain-reaction accident guide walks through it, and the multi-vehicle accident team handles them directly.
Curious how thin Nevada’s floor really is? Our breakdown of the state’s minimum car insurance requirements shows exactly why so many serious crashes exceed the coverage available.
How the money gets divided when several people are hurt
When claims exceed the available policy, the insurer doesn’t multiply the coverage — it divides it. The company pays out up to its per-accident limit and no further, leaving the rest of the damages uncovered by that one policy. How the pot gets split depends on the situation, and it’s rarely first-come, first-served in a way that’s fair to everyone.
Sometimes the insurer negotiates separate settlements with each claimant until the money runs out. Other times, when there are more claimants than coverage, the company files an interpleader — it hands the policy limit to a court and asks a judge to decide how to divide it among the injured parties. Either way, the people who documented their injuries clearly and made their claim early tend to be in a stronger position when the money is limited.
That’s why speed and evidence matter so much here. Waiting to see how you feel, skipping follow-up care, or handling it yourself can quietly weaken your share of a pool that’s already too small. How fault is sorted out between the drivers also shapes who pays what — our explainer on how fault is determined in a multi-car pileup covers how Nevada untangles a crash with several vehicles.
Alternative ways to recover when the at-fault policy runs out
A maxed-out policy is a starting point, not a dead end. In most serious Las Vegas multi-vehicle crashes, there’s more than one place to look for compensation.
Your own UM/UIM coverage
This is usually the most valuable protection you have, and many people don’t realize they’re carrying it. Under NRS 687B.145, every Nevada insurer has to offer you uninsured/underinsured motorist (UM/UIM) coverage at limits no lower than your liability coverage — you can only go without it if you rejected it in writing. When the at-fault driver’s policy is too small to cover your injuries, your own UIM coverage can step in and pay the gap, up to your limits. It’s your insurer, but it’s your money to claim. We cover how this plays out when the other driver’s policy falls short in our guide to UM/UIM after a head-on collision — the same principle applies in a pileup.
Other at-fault drivers’ policies in the chain
A multi-vehicle crash often has more than one negligent driver, and each one may carry their own policy. If two or three drivers share the blame for the wreck, there can be two or three separate sources of coverage to pursue — not just one. How much you can recover from each depends on how fault is apportioned in Nevada, which is why our comparative negligence guide for multi-vehicle crashes is worth reading before you accept any single insurer’s version of who caused what.
Umbrella policies
Some at-fault drivers carry a personal umbrella policy that adds coverage on top of their auto limits — sometimes a million dollars or more. An umbrella can be the difference between a thin recovery and a full one. It won’t cover everything, though: umbrella policies typically exclude the policyholder’s own injuries, intentional acts, and business or commercial-use claims. Finding out whether one exists usually takes a lawyer asking the right questions in discovery.
The at-fault driver’s personal assets
When coverage still isn’t enough and the at-fault driver has real assets — home equity, savings, a business — pursuing those personally may be an option. It isn’t the right move in every case, and a lawyer will tell you honestly when it’s worth it and when it isn’t.
What not to tell the insurance company after a multi-vehicle crash
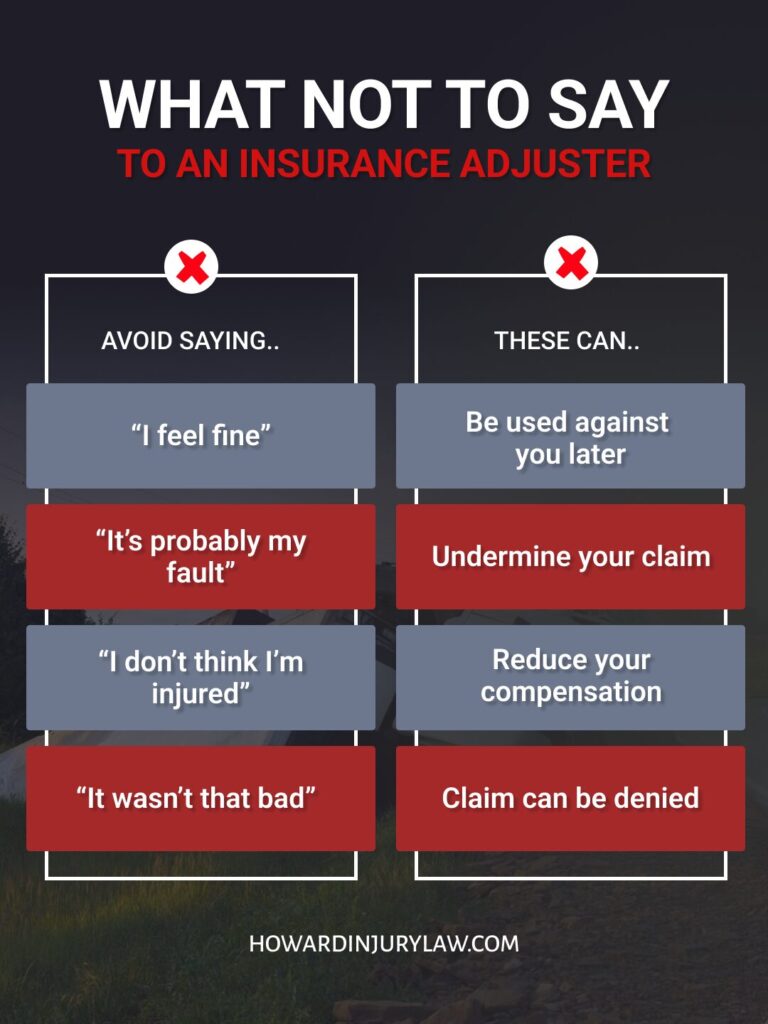
When coverage is limited, insurers have every reason to pay you as little as possible — and they’re skilled at getting injured people to help them do it. A few things to hold back:
- Don’t give a recorded statement to the at-fault driver’s insurer without talking to a lawyer. It exists to find words they can use to reduce your claim.
- Don’t guess or speculate about fault. “I didn’t see them” or “I might have been going a little fast” can be turned into shared blame that shrinks your share of an already-small pool.
- Don’t accept the first offer in a rush. Early offers in limited-coverage crashes are often designed to close your claim before you know the full extent of your injuries.
- Don’t sign a release until someone who works for you has confirmed it’s fair. Signing away your claim for one policy can cost you access to the others above.
Glen Howard spent years as an insurance defense attorney before he started representing injured people — he knows how these companies decide what to pay and where they look to cut. That’s the perspective working for you, not against you. When several insurers are involved in one crash, the dynamics get even more tangled; our piece on multiple insurance companies fighting over one crash shows how that plays out, and our multi-vehicle accident attorneys deal with it every week.
Frequently Asked Questions
Why is my insurance not covering everything?
Usually because the at-fault driver’s policy has a cap, and your injuries — or everyone’s injuries combined — exceed it. Nevada only requires $25,000 per person and $50,000 per crash in liability coverage, and that per-crash limit is shared among everyone hurt. Once it’s paid out, that policy is done, even if real damages are far higher. The good news is that the at-fault policy is often just one of several coverage sources. Your own UM/UIM coverage, other at-fault drivers’ policies, and umbrella policies can all fill the gap. A lawyer’s first job is to identify every policy in play before anyone tells you the money has run out.
What happens if the injuries are worth more than the insurance covers?
The at-fault policy pays up to its limit, and the remaining damages have to come from somewhere else. In Nevada, that “somewhere else” is often your own underinsured motorist (UIM) coverage, which is designed for exactly this shortfall. If more than one driver caused the crash, each of their policies may also be available. In some cases, the at-fault driver is personally responsible for damages beyond their coverage, and pursuing their assets becomes an option worth weighing. Which paths make sense depends on the specifics, so it’s worth having an attorney map the full recovery picture rather than assuming the first policy is your ceiling.
What will an umbrella policy not cover?
An umbrella policy adds liability coverage above an at-fault driver’s auto limits, but it has boundaries. It generally won’t cover the policyholder’s own injuries, damage they cause on purpose, or claims tied to business and commercial vehicle use. It also only kicks in once the underlying auto policy is exhausted. For you as the injured party, an umbrella can meaningfully increase what’s available to recover — but you usually only learn it exists if a lawyer requests the at-fault driver’s full coverage details during the claim.
Can I still get compensation if the at-fault driver is underinsured in Nevada?
Yes, in most cases. Underinsured doesn’t mean uncompensated. Under NRS 687B.145, your own policy likely includes UM/UIM coverage that steps in when the at-fault driver’s limits fall short — unless you rejected it in writing. Beyond that, additional at-fault drivers, umbrella policies, and sometimes personal assets can add to your recovery. Nevada also gives you two years from the date of the crash to file a lawsuit under NRS 11.190, and that window closes faster than most people expect while they’re still treating. Talking to a lawyer early keeps every option open.
Talk to a Las Vegas multi-vehicle accident lawyer before the money runs out
If you’re staring at a stack of medical bills and one small policy, the worst thing you can do is wait and hope the insurance company divides things fairly. In a limited-coverage crash, the people who move first and document best protect their share — and the ones who wait often watch the pool empty. You don’t have to figure out which policies apply on your own.
Howard Injury Law reviews multi-vehicle crashes at no cost, and you pay nothing unless we win — Nevada’s contingency model means our fee comes out of the recovery, not your pocket. Glen Howard’s background on the insurance defense side means we know where coverage hides and how adjusters decide what to pay. Call (702) 331-5722 or request a free case review, and we’ll tell you honestly how many sources of compensation your case actually has.
Every crash is different, and this article is general information rather than advice for your specific situation — the fastest way to know where you stand is a real conversation about your case. If you or your family also need support beyond the legal claim, HILhelps connects Las Vegas accident victims with community resources during recovery.