

You survived the head-on. Now you’re staring at a stack of medical bills, a missed paycheck, and a number from the other driver’s insurance company that doesn’t come close to covering any of it. That’s the moment an underinsured motorist claim exists for — when the at-fault driver in your Las Vegas crash had insurance, but nowhere near enough to pay for what a head-on collision actually does to a person.
If that’s where you are, you have more options than the at-fault driver’s policy limit. Here’s how the coverage works in Nevada, and what to do before you accept anything.
What happens when the at-fault driver’s coverage runs out
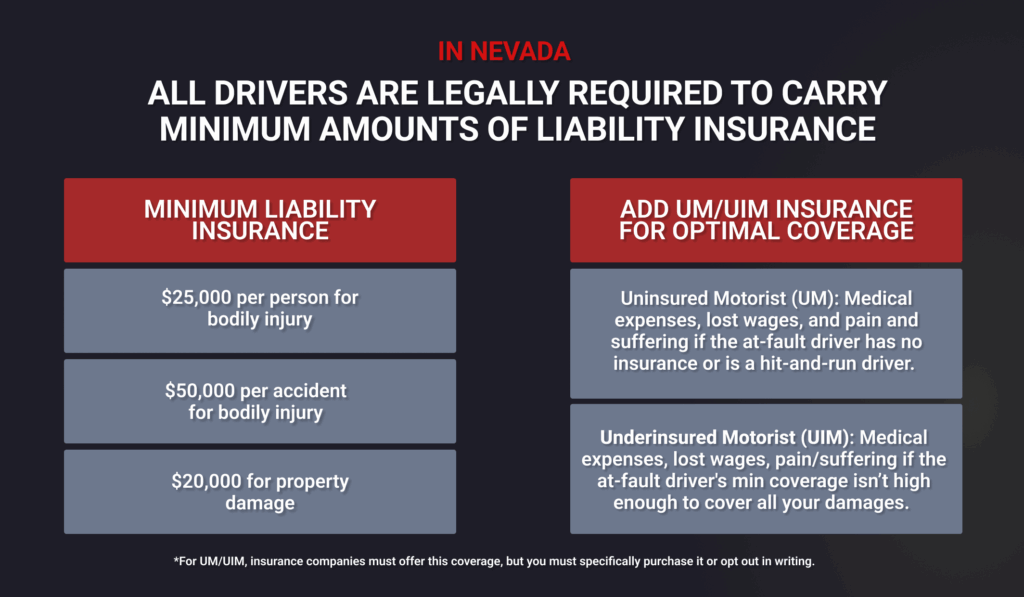
Nevada only requires drivers to carry $25,000 in bodily injury coverage per person (25/50/20). A head-on collision routinely blows past that in the first hospital day. Emergency surgery, a trauma admission, or an air-ambulance ride from a wrong-way wreck on I-15 or US-95 can each run tens of thousands of dollars on its own — before you’ve added lost wages, follow-up care, or the pain of a months-long recovery.
So the math breaks fast. The other driver’s insurer pays out its maximum, that check clears, and you’re still deep in the hole. That gap between what the at-fault policy covers and what your injuries actually cost is exactly the problem underinsured motorist coverage was built to solve.
How underinsured motorist coverage fills the gap in Nevada
Underinsured motorist (UIM) coverage is protection you carry on your own auto policy. When the at-fault driver’s liability limits get exhausted and your losses are still higher, your UIM coverage steps in and pays the difference — up to the UIM limit you selected.
In practical terms: the at-fault driver’s insurer pays its limit, and your UIM coverage covers your remaining documented damages above that amount, capped at your own policy’s ceiling. One important Nevada wrinkle — UIM only applies when your total damages actually exceed the at-fault driver’s limits. It’s not there to top off a low settlement; it’s there when your real losses run past what the other driver could ever pay.
Here’s the part most people don’t realize: you may already have this coverage without knowing it. Nevada law requires insurers to offer UM/UIM coverage equal to your bodily injury limits, and you can only decline it in writing. If you never signed a rejection form, there’s a good chance it’s sitting on your policy right now. Pull your declarations page and look — or have someone check it for you.
Uninsured vs. underinsured: which one applies to your crash
These two get lumped together as “UM/UIM,” but they answer different problems:
- Uninsured motorist (UM) covers you when the at-fault driver had no insurance at all — or fled the scene in a hit-and-run.
- Underinsured motorist (UIM) covers you when the at-fault driver had insurance, but the limits were too low to cover your injuries.
If the driver who hit you carried nothing, that’s a different path — start with our breakdown of when the driver had no insurance at all, and whether it’s worth pursuing an uninsured driver directly. This page is for the more common head-on scenario: real coverage on the other side, just not enough of it.
It’s your own insurer — and they can still fight you
You’d think filing against your own company would be simple. You’ve paid your premiums; now you need the coverage you bought. In reality, a UIM claim can be just as much of a fight as a claim against a stranger’s insurer.
Once you file, you stop being the loyal customer and become the person asking them to write a large check. Adjusters dispute whether your injuries are as serious as you say, argue over what counts toward the limit, and float lowball offers hoping you’ll take a fraction of the claim’s value while you’re stressed and behind on bills.
This is where Glen Howard’s background matters. Before founding Howard Injury Law, Glen worked as an insurance defense attorney — the lawyer the carriers hired. He knows how a UIM file gets evaluated internally, where the pressure points are, and how the other side decides what a claim is really worth. That perspective is hard to get from someone who’s only ever sat on one side of the table.
What to do now to protect your underinsured motorist claim
A few moves make a real difference to what you can recover:
- Find your declarations page. Confirm whether you carry UM/UIM and what the limit is. If you insure more than one vehicle, Nevada may also let you stack those limits — worth checking.
- Document everything. Keep every bill, imaging report, therapy note, and record of missed work. UIM pays on documented damages, so gaps in your paper trail become gaps in your recovery.
- Don’t rush to settle the at-fault claim. Settling the other driver’s policy too quickly, or for less than the full limits, can quietly cost you your right to UIM. Talk to a lawyer before you sign a release.
- Watch the deadlines — there are two. Your claim against the at-fault driver runs on Nevada’s injury deadline. Your UIM claim is a claim against your own insurer under your policy, and it follows different timing that can be shorter than you’d expect. Miss either and your recovery can end there, so confirm both early. Every policy and case is different — this is general information, not advice on your specific claim.
Frequently Asked Questions
What happens if the at-fault driver doesn’t have enough insurance in Nevada?
You’re not automatically stuck with the shortfall. Once the at-fault driver’s liability limits are paid out, your own underinsured motorist coverage can pay your remaining documented losses — medical bills, lost wages, and pain and suffering — up to the UIM limit on your policy. UIM applies when your total damages exceed what the at-fault driver’s policy could cover. If you also have MedPay or health insurance, those may help in the meantime. The key is not to accept the at-fault insurer’s limit as the end of the road. A Las Vegas attorney can map out every layer of coverage that could apply to your head-on crash before anything gets signed.
Do I need underinsured motorist coverage if I already have full coverage?
Yes — and this trips up a lot of Nevada drivers. “Full coverage” usually means liability plus collision and comprehensive. That protects your car and pays for damage you cause. It does nothing for your own bodily injuries when someone else hits you with too little insurance. Underinsured motorist coverage is a separate add-on that protects you and your passengers in exactly that situation. Given how many drivers on Las Vegas roads carry only the state minimum, UIM is often the most valuable protection on your policy — and the one people are surprised to learn they either have or wish they’d kept.
What should I not tell my insurance company after a head-on crash?
Report the crash promptly, but be careful how much you volunteer. Don’t guess about your injuries — saying “I feel fine” before you’ve been fully evaluated can be used to minimize a serious condition that surfaces days later. Don’t speculate about fault or replay the accident in theories. And don’t agree to a recorded statement before you’ve spoken with an attorney; those are often used to lock you into words that get twisted later. Stick to the basic facts — when, where, who was involved — and let your medical records and a lawyer tell the rest. On a first-party UIM claim especially, how the adjuster plays it matters more than people expect.
Will my rates go up if I file a UIM claim in Nevada?
Nevada law is on your side here. Under NRS 687B.385, an insurer cannot cancel your policy, refuse to renew it, or raise your premium because of a claim for an accident you weren’t at fault for — and a UIM claim after someone else caused a head-on is exactly that kind of claim. The Nevada Supreme Court has upheld this protection. So the common fear that “using my own coverage will punish me” generally doesn’t hold up for a not-at-fault UIM claim. You paid for that coverage precisely for a moment like this. Letting the fear of a rate hike stop you from using it usually just leaves money on the table.
Injured in a head-on and the coverage won’t cover it? Let’s find the money that will.
The at-fault driver’s limit is a starting point, not a ceiling. Between your underinsured motorist coverage, stacked policies, and other layers most people never think to check, there’s often far more available than the first offer suggests — and figuring that out is exactly what we do.
Talk to a Las Vegas head-on collision lawyer at Howard Injury Law before you accept anything or sign a release. Glen Howard spent years on the insurance company’s side of these claims; now he uses that against them for people like you. The consultation is free, and there’s no fee unless we win your case.
Call (702) 331-5722 or reach out through our contact page — bring your declarations page if you have it, and we’ll tell you what coverage you’re actually working with.